Capital One Mobile

Screenshots
Details
- Rating
- 648.52K reviews
- Version
- 6.37.5
- Developer
- Capital One Services, LLC
Analysis by Norviv
I tend to judge a banking app less by its first impressive moment than by whether it still saves me effort after the novelty wears off. Capital One Mobile makes a strong first impression because routine jobs—checking activity, paying a bill, or dealing with a card—are meant to be handled on a phone. Its lasting value, though, depends on whether you already use Capital One and whether you prefer managing those tasks in one place rather than switching between a bank website and separate tools.
A useful first week, not a reason to change banks
The app is a free finance app from Capital One Services, LLC, and it has been available since July 29, 2011. Its broad adoption—over 50 million installs and an average rating of 4.5 from around 1.7 million ratings—suggests that it serves a familiar, practical need. Those figures are reassuring context, but they do not tell me whether it is right for someone whose accounts are elsewhere: the main benefit is managing Capital One products, not replacing every financial service you use.
In the first few days, the convenience is easy to understand. If you already have a Capital One account, opening the app to check a balance or recent activity can be quicker than sitting down at a computer. The experience is particularly appealing when you need to handle a small task immediately instead of adding it to a list for later. I would think of it as a mobile control panel for an existing banking relationship, rather than a reason by itself to open one.
The routine that makes it worth keeping
After the novelty fades, the best case for keeping the app is its role in recurring habits. A quick look at activity after a purchase can help you spot something unexpected while the details are still fresh. Setting a reminder or alert that suits your own routine can also make a bill less likely to slip past unnoticed. These are modest gains, but modest gains are exactly what I want from a tool I use throughout the year: fewer steps and fewer avoidable surprises.
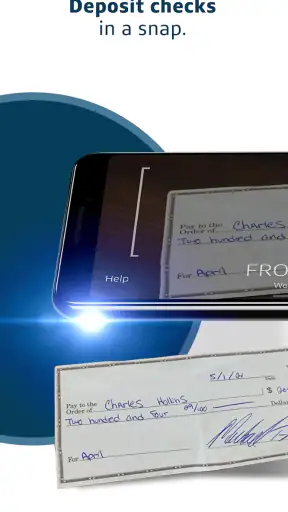
A realistic example is a busy weekday when a bill comes due while you are away from your laptop. You can use the app to review the relevant account and take care of the payment rather than waiting until you get home. For a paper check, mobile deposit can save a trip, although I would still pause to frame the check clearly and review the on-screen instructions before submitting it. A phone makes the task more convenient; it does not make careful checking unnecessary.
Why Capital One Mobile Stands Out
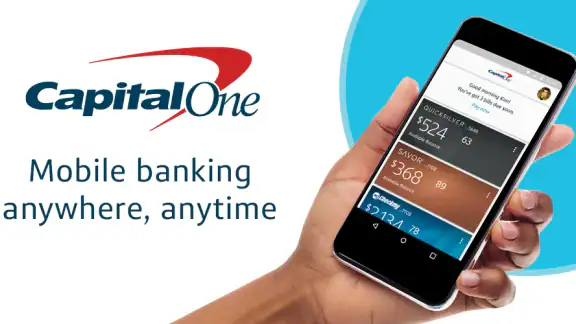
First things first, the interface is super user-friendly. You know how some apps feel like you need a degree to navigate? Not with Capital One Mobile. Everything is laid out clearly, making it easy to find what you need without getting lost in a sea of options.
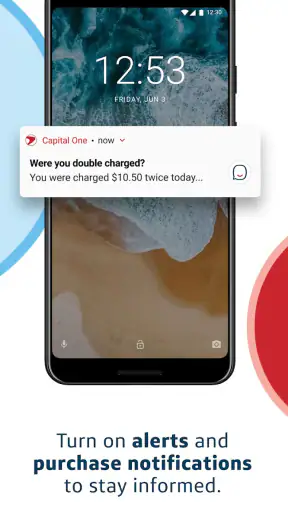
One of my favorite features is the real-time notifications. Every time there's a transaction, you get a ping. It's like having a watchdog for your wallet. This is especially handy for keeping an eye on your budget and ensuring no sneaky charges slip through.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
Features That Make Life Easier
Let's talk about the cool stuff. Need to deposit a check but don’t want to hit the bank? Just snap a photo with your phone and voilà, it’s done. Seriously, it feels like magic. Plus, you can easily pay bills or transfer money between accounts with just a few taps.
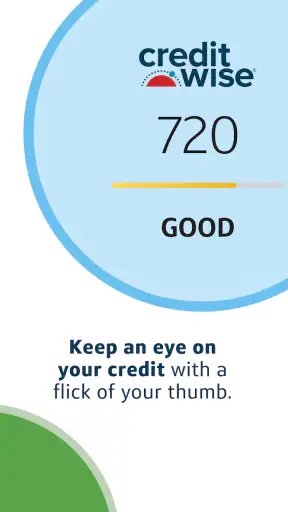
And for those of us who are always on the go, the app’s credit score tracking tool is a gem. It's updated regularly, so you can keep tabs on your score without having to dig through paperwork or log into separate websites.
Small choices that improve the everyday workflow
One practical habit I recommend is treating notifications as prompts to review, not as a complete record of your finances. A transaction alert can bring a purchase to your attention quickly, but the useful follow-up is to open the activity view, check the amount and merchant, and decide whether it belongs in your own budget. If every alert is left to accumulate unread, the feature can turn into background noise rather than protection.
Mobile check deposit is most helpful when convenience matters more than having a teller nearby. I would use it for an occasional check, follow the capture guidance carefully, and confirm that the submission is complete before putting the paper away. The trade-off is that a phone camera and a clear image are part of the process; if the image is hard to read or the app asks for another step, a branch or another accepted deposit method may be less frustrating. That is a useful distinction for anyone deciding whether the feature fits their usual banking.
Bill payment also rewards a little planning. I find it sensible to review the payee and amount before confirming, especially when handling a bill in a hurry. The phone is convenient for acting on a known obligation, while a larger screen may be more comfortable when reviewing several bills or comparing details. For a single routine payment, the app can reduce friction; for a complicated money task, convenience should not replace a careful final check.
When a banking app is not the whole answer
Compared with a generic budgeting app, a bank’s own app is strongest at account-specific tasks: viewing Capital One activity, managing a card, and completing banking actions. A dedicated budget tool may suit you better if your priority is building a detailed plan across accounts from several institutions or categorizing spending in a way tailored to your household. I would not expect one bank app to replace every spreadsheet, budgeting method, or financial service someone already relies on.
The same distinction matters if you mainly want a broad view of money held at different banks. Capital One Mobile is naturally most compelling when Capital One is central to your day-to-day finances. If you have no Capital One account, or you are looking for a neutral dashboard for unrelated accounts, the app is unlikely to become your main finance hub. In that situation, your existing bank’s app or a tool designed around a cross-provider overview may be a better fit.
It is also worth thinking about how you handle access. Signing in on a phone is convenient, but people who share devices, avoid biometric sign-in, or prefer keeping financial activity off a mobile screen may be happier with a browser or in-person service for some tasks. Card locking can be useful when a card is misplaced, yet it is not a substitute for contacting the bank when a situation needs more help than a quick self-service action. I see the app as a practical first stop, not a promise that every banking problem can be solved without assistance.
Security and control need sensible habits
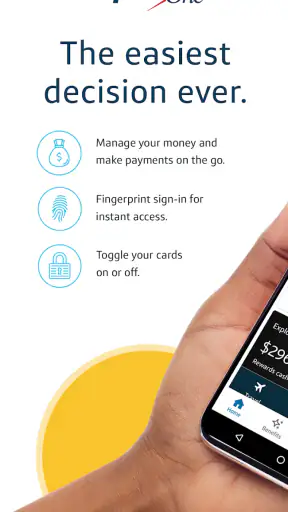
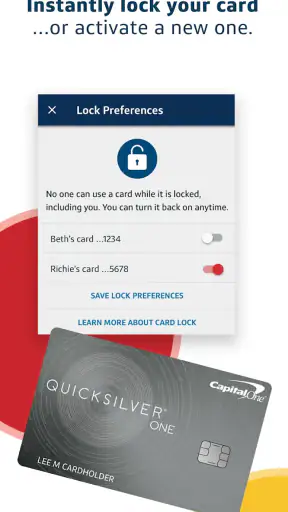
Now, I know what you're thinking—how safe is it? Capital One takes security seriously. They use top-notch encryption, and if you ever misplace your card, you can lock it directly from the app. Talk about peace of mind!
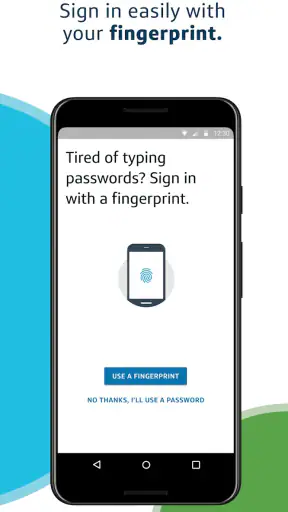
There’s also the handy feature of setting up a fingerprint or face ID login. This way, even if your phone ends up in the wrong hands, your financial info stays secure.
Those controls are reassuring, but I would still treat device security as part of banking security. A lock on the phone, a private sign-in method, and attention to notifications matter because financial details can appear in everyday phone use. If you lose a card, locking it is a useful immediate action; if you suspect unauthorized activity, review the account and use the bank’s support options rather than assuming that one tap has resolved the whole issue.
For someone who checks balances often, the habit can be helpful without becoming compulsive. I prefer choosing a couple of natural moments—after a cluster of purchases or before paying bills—rather than opening the app every time a notification appears. That keeps the information useful while reducing the feeling that I need to monitor every small movement. A finance app should support calm decisions, not make money management feel like a stream of alarms.
What can become tiring over time
Alerts are a good example of a feature that can either help or wear you down. A useful transaction notice can make unfamiliar activity stand out, but too many interruptions can train you to ignore all of them. I would start with the notifications that solve a real problem for you, such as keeping an eye on spending or remembering due dates, then adjust the setup if it becomes distracting. The best configuration is personal; more alerts are not automatically better.
There is a similar trade-off with keeping all routine banking on a phone. It is fast for a balance check or a straightforward payment, but a small screen can make careful review less comfortable when you are tired, rushed, or handling an unfamiliar transaction. I would move a task to a computer or contact support if I needed more room to compare details or felt unsure about what I was confirming. Choosing another route is not a failure of the app; it is good judgment about the task.
Feature expectations should also stay grounded. The app brings several Capital One tasks together, but it is not automatically a full household financial planner. Credit score tracking can be a convenient reference point, while people making a major borrowing decision may want to examine their broader financial picture rather than rely on one in-app number. I like having a quick view available, but I would not confuse convenience with a complete financial assessment.
Little Extras That Count
One thing I really appreciate is the app's design. It's clean, modern, and doesn’t bombard you with ads or unnecessary fluff. Plus, the customization options are a nice touch. You can set up alerts for due dates or spending thresholds, which helps in managing finances without any stress.
And get this: there's a chatbot feature! It's like having a conversation with a financial advisor who never sleeps. Whether you have questions about transactions or need help with the app, the bot’s got your back.
I would use the chatbot for a quick orientation question or a straightforward query, then switch to the bank’s other support routes if the issue is sensitive, complicated, or requires a person to understand context. That is a practical way to think about automated help: it can reduce the effort of finding a starting point, but it should not be mistaken for personal financial advice or a guarantee that every case can be settled in a chat.
The app is rated for Everyone, and its current version is 6.37.5, with iOS 11 as the minimum operating-system requirement. Those details matter when deciding whether an older device can run it, but the bigger question is whether you want banking actions available on your phone. If you prefer not to manage money on a mobile device, a website, a branch, or the service offered by another institution may suit you better.
Who will get the most from it
I would recommend it most readily to someone who already uses Capital One and wants everyday account tasks close at hand: checking activity, paying a bill, depositing a check, or responding when a card is misplaced. It is also a sensible choice for people who like having a credit score view alongside their banking rather than signing in to another site for a quick check. The recurring value comes from doing these small jobs reliably, not from exploring every feature once.
On the other hand, I would skip it as a primary finance app if you do not bank with Capital One, need a comprehensive budget across multiple providers, or strongly prefer handling financial matters on a computer. I would also avoid depending on mobile alerts as my only way to remember bills; alerts are helpful backup, while a routine you trust is more dependable. The right app should match your habits, not force you to build new ones around notifications.
As a finance app, it has been around since 2011, and its current version is 6.37.5. For me, that history and its large user base are background reassurance rather than the main selling point. What matters more is whether the app makes a repeated task simpler in your own week. If your Capital One account is already part of your daily finances, that is an easy test: use it for a normal balance check, a bill, or a card-related need and see whether it genuinely removes steps.
In conclusion, Capital One Mobile is not just a banking app; it’s a personal finance companion. From its intuitive design to robust security features, it’s clear why it's a favorite for many. So, if you're looking for convenience in managing your finances, this app is definitely worth checking out.
Does it earn a lasting place?
My verdict is that it can earn that space, but mainly through maintenance rather than novelty. Once the first-week appeal of handling banking from a phone passes, the app’s value is in a steady rhythm: check activity when useful, pay routine bills, use a deposit workflow when it saves a trip, and keep card controls accessible. If those actions are already part of your life with Capital One, having them together is a practical convenience.
I would not install it expecting it to replace a bank relationship, a full budgeting system, or careful decision-making. Its strongest role is narrower and more useful: making common Capital One tasks easier to fit into ordinary days. For the right customer, that is enough reason to keep it. For someone whose accounts and habits point elsewhere, choosing a different tool is the more sensible long-term choice.
Frequently Asked Questions
01What features does the Capital One Mobile app offer?
The Capital One Mobile app provides a comprehensive suite of features designed to manage your finances efficiently. Users can check account balances, view transaction history, and make payments. The app also allows for mobile check deposits, setting up alerts, and accessing credit scores. Additionally, it includes tools for budgeting and monitoring spending patterns.
02How secure is the Capital One Mobile app?
Security is a top priority for the Capital One Mobile app. It employs advanced encryption methods to protect your data. The app also features multi-factor authentication and customizable security alerts. Users can set up biometric login options like fingerprint or facial recognition for added security. Regular updates ensure the app stays ahead of potential threats.
03Can I manage multiple accounts with the Capital One Mobile app?
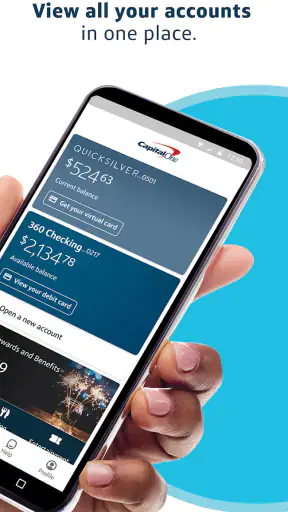
Yes, the Capital One Mobile app allows users to manage multiple accounts seamlessly. Whether you have savings, checking, or credit card accounts, you can access and manage them all from a single interface. The app provides a comprehensive view of all your accounts, enabling easy tracking and management of your finances.
04Does the Capital One Mobile app support mobile deposits?
The app supports mobile check deposits, which is a convenient feature for users. You can deposit checks directly from your smartphone by taking photos of the check front and back. The process is straightforward and secure, with clear instructions provided within the app to guide you through each step.
05Is the Capital One Mobile app user-friendly for beginners?
The Capital One Mobile app is designed with user-friendliness in mind, making it accessible for beginners. It features an intuitive interface with easy navigation. The app includes helpful tutorials and a support section for users needing assistance. Whether you're tech-savvy or not, the app offers a seamless user experience.


